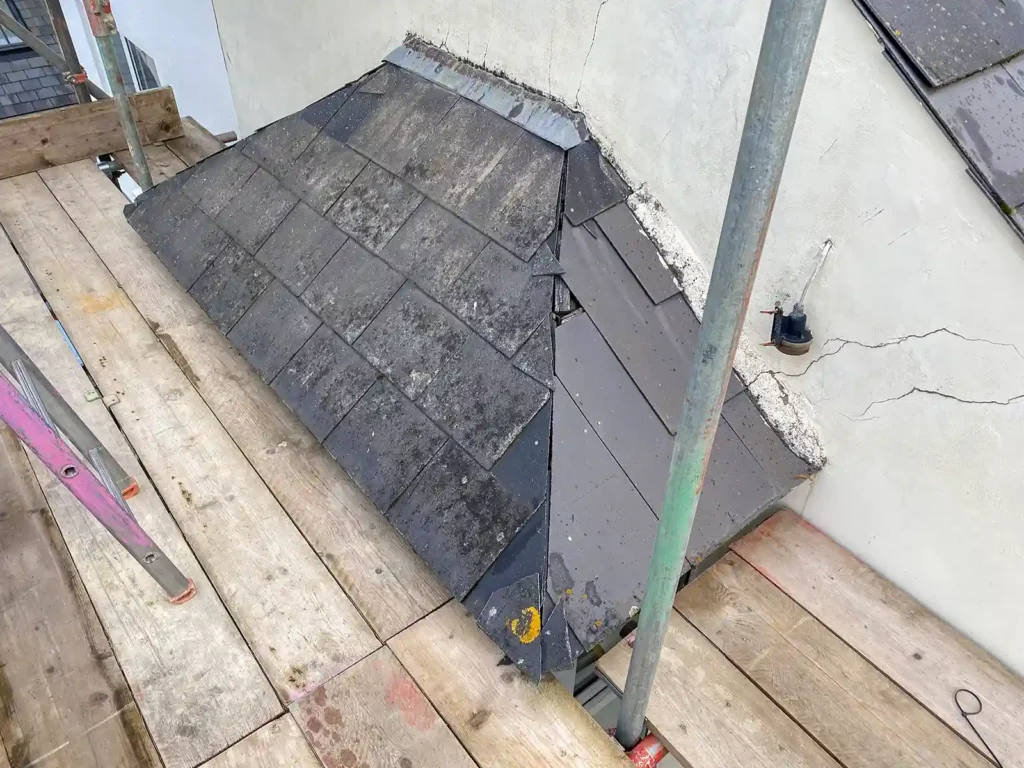
When a roof is damaged, one of the first questions is who pays. This is general information, not insurance advice, and every policy is different, so always check your own policy documents and speak to your insurer. Will insurance pay for roof damage? It depends on the cause, as this guide explains.
What buildings insurance often covers
Many buildings policies cover sudden, unexpected damage, such as storm damage or a tree falling on the roof. The damage is usually something that happened at a particular time, such as a named storm.
What it often does not cover
- Wear and tear, and the roof simply getting old
- Damage caused by poor maintenance, such as blocked gutters or moss
- Gradual leaks that built up over time
- Faults from poor original workmanship
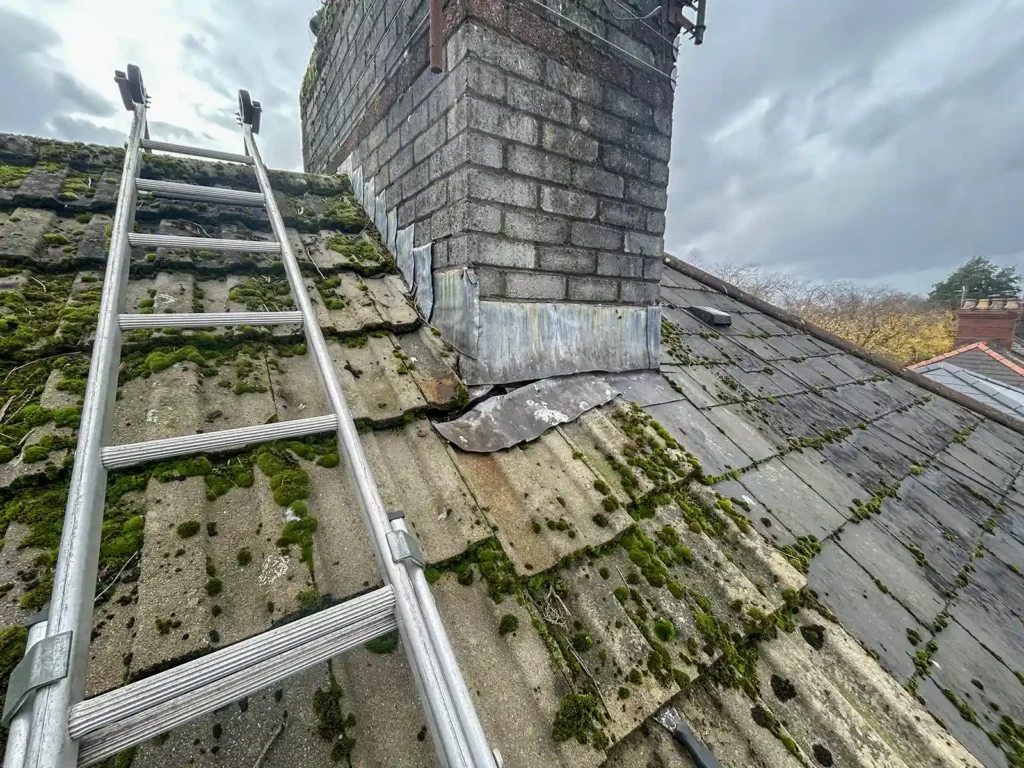
Practical steps if you need to claim
- Take photos and video of the damage as soon as it is safe, with dates
- Take reasonable steps to stop further damage, for example a temporary repair
- Contact your insurer before major repairs, and ask what evidence they need
- Ask your roofer for a written description of the damage and the cause
- Keep all invoices and reports
Sudden damage versus gradual damage
Insurers tend to distinguish between damage that happens suddenly, such as a storm tearing off tiles, and damage that builds up gradually, such as a worn roof starting to leak. The first is more likely to be covered. The second is often treated as maintenance, which is the homeowner’s responsibility. That is why a record of regular roof maintenance can matter.
Evidence that helps a claim
- Dated photos or video of the damage, inside and out
- Photos of the roof before the damage, if you have them
- A written report from a roofer describing the damage and cause
- Invoices for any temporary repairs and permanent work
- Records of past maintenance and inspections
Reasonable steps and temporary repairs
Most insurers expect you to take sensible steps to prevent further damage, such as arranging a temporary repair to make the roof watertight. Keep the receipts, and tell your insurer what you have done. Do not start major repair work until you have checked what your insurer needs, unless it is urgent to protect the property.
Excess, claims history and your premium
Policies usually have an excess, which is the amount you pay towards a claim. Claims can also affect future premiums, so some homeowners decide to pay for smaller repairs themselves. Your insurer or broker can explain how your policy works.
A roofer is not an insurance assessor
A roofer can describe what is wrong, make the roof safe and carry out repairs. They cannot decide whether a claim will be paid. That decision rests with your insurer.
Keeping the roof maintained helps
Insurers can refuse a claim when damage comes from lack of maintenance, so a record of regular checks is useful. Ask for a written condition report after each visit.
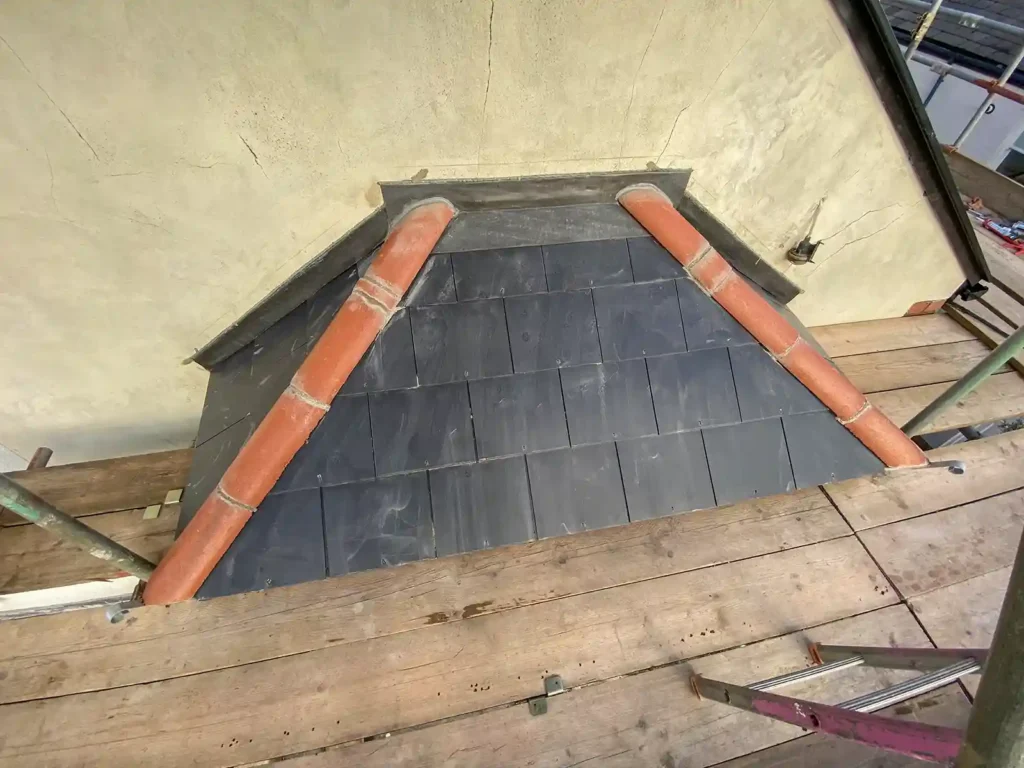
A roofer can describe the damage and make the roof safe, but only your insurer can decide on a claim. If you need the roof made safe, see our emergency roof repairs, and our roof maintenance service for regular checks.
Roof maintenance and insurance
Regular roof maintenance does not guarantee that a claim will be paid, but it shows that the roof has been looked after and helps you spot problems early. Keep each written condition report and any repair invoices together, so you have a clear history of the roof if you need it.
If a claim is refused
If your insurer declines a claim, ask them to explain in writing which part of the policy applies. You may be able to ask for a review, or use the insurer’s complaints process. Independent advice is available for disputes.
Keep your insurer informed
If your roof work was paid for through insurance, tell your insurer when it is complete and send them the invoice and any guarantee. Keep copies of everything, and note names and dates of conversations. Good records make any future claim easier.
Check what your policy says about roofs
Every policy is different. Some mention maintenance conditions, excesses specific to storm damage or exclusions for older roofs. Reading the roof-related sections of your policy now means there are no surprises later.
Roof insurance FAQs
Does home insurance cover a leaking roof?
It depends on the policy and the cause. Sudden damage is more likely to be covered than wear and tear. Check your policy and speak to your insurer.
Will insurance pay for a new roof?
Not usually for an old roof wearing out. It may help if a roof is damaged by an insured event such as a storm.
What evidence should I keep for a roof claim?
Photos, dates, a roofer’s written report and all invoices and receipts.
Should I arrange repairs before contacting my insurer?
Make the roof safe if needed, and keep receipts, but contact your insurer before major repairs.
Can you provide a written report for insurance?
We can describe the damage and the work carried out. Your insurer makes the decision on any claim.
More about insurance pay for roof damage
If you disagree with an insurer’s decision, the Financial Ombudsman Service explains how to complain.
Worried about your roof?
Call now to book a free roof inspection and get a fixed price in writing.